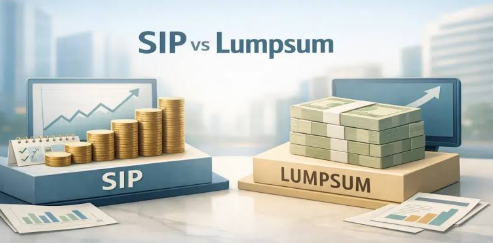
When it comes to investing in Mutual Funds schemes, the most common question which arises in investor’s mind is about how much and when they should invest. There are broadly two ways to invest in a Mutual Fund scheme, the first is to make a lumpsum payment and the second is through a Systematic Investment Plan or SIP. A detailed comparison between these two different modes of investment is required to understand the impact of change in timing on the value of Mutual Fund schemes. A brief overview and some examples will help us understand the difference between the two investment options.
What Is Lumpsum Investing?
Lumpsum investing involves putting a larger amount into a mutual funds scheme in one go. Once the units are allotted, the entire amount remains exposed to the scheme’s market movements.
For example, if someone invests ₹1,20,000 in a mutual fund scheme, the value of the investment will depend on the applicable NAV and how it changes over the investment period. The final value also depends on the duration of the investment and the performance of the scheme’s underlying assets.
What Is SIP Investing?
A Systematic Investment Plan, or SIP, allows an investor to put a fixed amount into a mutual fund scheme at regular intervals, usually monthly. It is a way to invest periodically rather than commit the entire amount at once.
For example, if an investor puts ₹10,000 into a scheme every month for 12 months, the total investment will be ₹1,20,000. The number of units purchased may differ with each instalment because the applicable NAV may change. Each instalment is also exposed to market movements from the time the units are allotted.
Lumpsum vs SIP: A Numerical Comparison
The table below compares the two methods using a few common factors.
| Factor | Lumpsum | SIP |
| Investment amount example | ₹1,20,000 at once | ₹10,000 every month for 12 months |
| Investment timing | The entire amount is invested at once | Money is invested periodically |
| Unit allocation | Units are allotted at the applicable NAV | Units are allotted at the applicable NAV for each instalment |
| Market exposure | The entire amount is exposed from the start | Each instalment is exposed from its investment date |
| Return calculation | Depends on the amount invested, timing, and investment period | Depends on each instalment, its timing, and the applicable NAV |
| Investment discipline | Requires the full amount at once | Allows regular investments from periodic income |
Example to Illustrate How the Numbers May Differ
Let us assume that an investor has ₹1,20,000 to invest over a year. They could invest the full amount at the beginning or put ₹10,000 into the scheme every month.
If the NAV rises steadily throughout the period, the lumpsum investment may have a higher value at the end because the entire amount was invested earlier. However, if the NAV falls after the lumpsum investment and later recovers, the SIP may benefit from buying units at lower NAVs during some instalments.
The outcome depends on how the NAV changes and when each investment is made. Neither method produces higher returns in every market situation.
Factors to Consider Before Choosing
A few factors help explain how these investment methods differ.
1. Amount to Be Invested
For a lumpsum investment, the full amount needs to be available at the time of investment. With an SIP, the investor puts in smaller amounts at regular intervals. To compare the methods, it helps to consider the same total investment amount. However, the timing of each contribution also affects the final value.
2. Market Conditions
Market movements affect both methods, but the timing of investment differs. With a lumpsum investment, the entire amount enters the market at once. With an SIP, each instalment enters at a different time. Short-term market movements alone do not determine which method will perform better, and past trends do not indicate future returns.
3. Period of Investment
The investment period affects the value of both approaches. In a lumpsum investment, the full amount is exposed to market movements from the start. With an SIP, earlier instalments remain invested for longer than later ones. A fair comparison should use the same final evaluation date and account for the different investment dates.
4. Calculation of Returns
An SIP calculator app helps estimate the possible value of regular investments using an assumed rate of return and investment period. A lumpsum calculator estimates the future value of a one-time investment based on the initial amount, assumed return, and duration.
These calculations provide estimates, not actual or assured returns. The final value depends on the scheme’s performance and changes in its NAV.
Conclusion
The main difference between lump sum and SIP is that the lump-sum investment exposes the full amount to market movements from the start, whereas SIP reduces the market risk by spreading the investment. However, both these modes of investment carry some amount of risk and cannot assure to give favourable investment outcome. The amount, the timing of the investment, and time of investment horizon play a vital role in determining the value of the investment. Investment tools provided by platforms like 5paisa can help individuals understand and compare the two investment options and estimate possible investment values before making a decision.